Insurance underwriters play an important role in deciding who and what an insurance company is willing to insure. They evaluate insurance applications, assess risk, and help determine whether coverage should be offered and, if so, at what price and under what terms.
In simple terms, an insurance underwriter decides whether a person, property, or business represents an acceptable risk for an insurance company.
While much of the underwriting process now involves data and automated technology, underwriters still use their knowledge and judgment to evaluate risks, particularly when an application is unusual or complex.
If you’re considering a career in insurance, understanding underwriting can also help you see how different roles within the industry work together.
What Is Insurance Underwriting?
Insurance underwriting is the process an insurance company uses to evaluate risk before agreeing to provide coverage.
Insurance works by collecting premiums from policyholders and using that money to pay covered claims. To make that system work, insurance companies need to understand the likelihood and potential cost of future losses.
That’s where underwriting comes in.
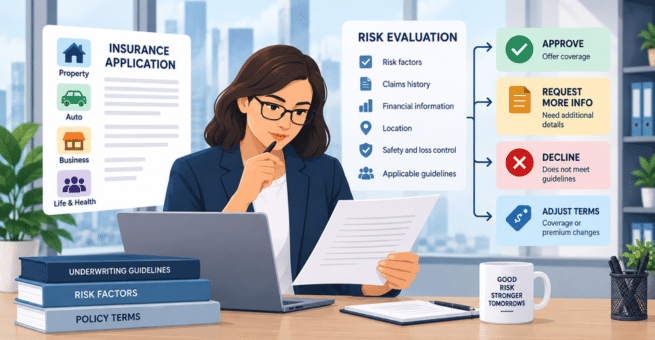
An underwriter reviews information about an applicant and compares that risk against the insurance company’s underwriting guidelines. Depending on the application, the underwriter may:
- Approve coverage
- Decline coverage
- Request additional information
- Determine how much coverage can be offered
- Help determine the appropriate premium
- Apply certain conditions or restrictions to the policy
The ultimate goal is to balance risk. An insurance company needs to take on enough business to generate premium revenue without accepting so much risk that paying out claims becomes unsustainable.
What Does an Insurance Underwriter Look At?
The information an underwriter evaluates depends heavily on the type of insurance being purchased.
For property and casualty insurance, an underwriter might consider factors such as the location and condition of a property, previous claims, driving records, the type of business being insured, safety measures, or potential exposure to losses.
A commercial underwriter evaluating a business, for example, may need to understand the company’s operations, property, employees, previous losses, and other factors that could increase or decrease risk.
Life and health underwriting uses different information because the risks being evaluated are different.
According to the U.S. Bureau of Labor Statistics (BLS), most insurance underwriters specialize in one of three broad areas: property and casualty, life, or health insurance. Property and casualty underwriters may specialize even further in commercial or personal insurance or in particular types of coverage.
What Decisions Does an Insurance Underwriter Make?
An underwriter isn’t simply deciding “yes” or “no” on an insurance application.
When an application is acceptable, the underwriting process can also help determine the amount of coverage and premium associated with the policy. Underwriters may also need additional information before they can make a final decision.
Consider someone applying for homeowners insurance. The insurer may need to evaluate the home’s age, construction, location, condition, previous claims, and other characteristics.
For a business, the questions could be much more complicated. What does the company do? How many employees does it have? What type of property or equipment does it own? What kinds of accidents or lawsuits could occur?
Underwriters take relevant information and determine whether the risk fits within the insurer’s guidelines.
Types of Insurance Underwriters
Although the basic purpose of underwriting remains the same, underwriters often specialize.
Property and Casualty Underwriters
Property and casualty (P&C) underwriters evaluate risks involving property and liability. That can include homes, automobiles, and businesses.
Within P&C insurance, underwriters may work with either personal lines or commercial lines.
Personal lines generally involves coverage purchased by individuals, such as homeowners and auto insurance. Commercial lines involves insurance designed for businesses and organizations.
Life Insurance Underwriters
Life insurance underwriters assess the risks associated with issuing life insurance coverage. The underwriting criteria are different from P&C because the insurer is evaluating risks related to the insured person’s life rather than a home, vehicle, or business.
Health Insurance Underwriters
Health insurance underwriting involves evaluating risk associated with health coverage. The rules governing health insurance and the factors insurers are permitted to consider can vary depending on the type of coverage and applicable laws.
How Do Insurance Underwriters Work With Insurance Agents?
Insurance agents and underwriters have different jobs, but the two roles often work closely together.
An insurance agent, broker, or producer generally works with customers to identify insurance needs, explain coverage options, submit applications, and sell policies. Depending on the position, producers may represent one insurance company or work with several carriers.
An underwriter generally works on the insurance company side of that process. The underwriter evaluates the application and determines whether the risk meets the carrier’s requirements.
In fact, the BLS describes underwriters as an important link between insurance companies and insurance sales agents.
For example, an agent working with a business owner might submit an application for commercial property insurance. If the underwriter needs more information about the building, operations or previous claims, the underwriter may work with the agent to obtain it.
This relationship is one reason understanding underwriting can be useful even if you plan to become an insurance agent rather than an underwriter. Agents who understand what carriers look for may be better prepared to submit complete applications and communicate effectively with underwriting teams.
How Does Underwriting Affect Policyholders?
Consumers may never speak directly with an underwriter, but underwriting can affect several important parts of their insurance coverage.
The underwriting process may influence:
- Whether an insurer offers coverage
- How much coverage is available
- The premium charged for the policy
- Whether additional information is required
- Certain conditions associated with the coverage
This is also why two people or businesses seeking similar insurance may not necessarily receive identical results. Their individual risk characteristics can be different.
Underwriting allows the insurance company to evaluate those differences.
Do Insurance Underwriters Use AI and Automation?
Technology has become a major part of modern insurance underwriting.
Underwriters have long used specialized software to analyze applications and risk factors. Increasingly sophisticated automation can now process information, evaluate risk criteria, and make recommendations much faster than a person could manually.
For relatively common and straightforward risks, technology may handle a significant portion of the process. The BLS notes that underwriters commonly rely on automated recommendations for simpler types of insurance such as auto coverage.
But that doesn’t mean every underwriting decision is automatic.
More unusual or complicated risks may require an underwriter to interpret information, obtain additional documentation, and make a judgment that isn’t as straightforward. The BLS specifically notes that complex insurance risks can require greater analytical insight from an underwriter.
Technology is changing the profession, but it is also changing what underwriters spend their time doing. Routine decisions can increasingly be automated, leaving human underwriters to focus more heavily on complex risks and decisions requiring analysis.
How Do You Become an Insurance Underwriter?
There isn’t one universal path into insurance underwriting.
According to the BLS, insurance underwriters typically need a bachelor’s degree, and employers often prefer candidates with degrees or coursework related to business, finance, economics or mathematics. However, candidates with an associate degree or high school diploma combined with insurance-related work experience may also qualify for some positions.
New underwriters also typically receive substantial training after they’re hired. Beginning underwriters may work under the supervision of experienced underwriters while learning how to evaluate basic applications and identify common risk factors.
As they gain experience, underwriters can move into more complicated risks and may eventually advance into senior underwriting or management positions.
Professional insurance certifications and designations can also be useful for career development.
Do You Need an Insurance License to Become an Underwriter?
An insurance producer license is not generally listed as a standard requirement for becoming an insurance underwriter.
This is an important distinction because insurance licensing requirements are often associated with agents and producers who sell, solicit, or negotiate insurance.
Underwriting is a different function.
The BLS identifies education, insurance-related experience, on-the-job training, and optional professional certifications as common components of an underwriting career. It does not identify obtaining a producer license as a typical entry-level requirement for the occupation.
Requirements can vary by employer and position, however, so candidates should always review the qualifications for a specific underwriting job.
Insurance experience can still be valuable. Someone who begins their career as an insurance producer or in another insurance-related position may develop knowledge of policies, coverage, terminology, and carrier processes that could be useful if they later pursue underwriting. To work as a producer or adjuster, you will usually need the appropriate license to begin working in those insurance fields. So while you don’t necessarily need a license to become an underwriter, you will need one if you plan to work as a producer and gain experience before moving to underwriting.
What Skills Do Insurance Underwriters Need?
Successful underwriting requires more than simply knowing insurance terminology.
Underwriters routinely evaluate large amounts of information and make decisions that have financial consequences for an insurance company. The BLS identifies several qualities that are particularly important for the occupation, including analytical, decision-making, interpersonal and math skills, along with attention to detail.
Communication matters, too. Underwriters may need to work with agents, brokers, other insurance professionals, medical professionals, or outside sources to gather information and explain underwriting decisions.
That combination of analysis and communication makes underwriting a good fit for people who enjoy working with information but don’t necessarily want a career centered primarily on sales.
How Much Do Insurance Underwriters Make?
According to the latest BLS Occupational Outlook Handbook data, the median annual wage for insurance underwriters was $81,370 in May 2025.
“Median” means half of workers in the occupation earned more than that amount and half earned less.
Actual salaries vary considerably based on experience, location, employer, specialty, and level of responsibility. BLS data show that the lowest 10% of insurance underwriters earned less than $55,530, while the highest 10% earned more than $145,160 in May 2025.
Is Insurance Underwriting a Good Career?
Whether underwriting is a good career depends on what you’re looking for.
It may appeal to people who enjoy:
- Analyzing information
- Solving problems
- Evaluating risk
- Working with numbers and data
- Making decisions
- Learning how businesses and insurance policies work
- Working in an office or professional environment
It’s also important to understand how technology is affecting the occupation.
The BLS projects employment of insurance underwriters to decline 4% between 2025 and 2035, largely because automated underwriting software allows insurers to process more applications efficiently. However, BLS still projects approximately 6,800 underwriting job openings each year, on average, during that period as an aging workforce leaves the occupation or retires.
For someone considering the field, that makes analytical skills, insurance knowledge, and the ability to handle complex risks particularly valuable.
Underwriters Are One Part of a Much Larger Insurance Industry
One of the benefits of working in insurance is the variety of career paths available.
Underwriters evaluate risk before and during the process of issuing insurance. Insurance agents and producers help consumers and businesses find and purchase coverage. Claims adjusters and examiners become involved when a loss occurs and a claim needs to be evaluated.
There are also careers in actuarial science, risk management, customer service, compliance, management, marketing, and many other areas.
For people interested in the sales and customer side of the industry, becoming a licensed insurance agent or producer can be one way to get started. Licensing requirements vary by state and by the type of insurance you want to sell, so it’s important to understand your state’s requirements before beginning your training.
At All-Lines Training, we offer insurance licensing and exam preparation courses designed to help future agents and producers prepare for their state licensing requirements and take their first steps into the insurance industry.
Explore Insurance Licensing Courses
Frequently Asked Questions About Insurance Underwriters
What does an insurance underwriter do?
An insurance underwriter evaluates an insurance application and determines whether the insurer should accept the risk. For approved applications, underwriting also helps determine appropriate coverage and premiums.
What is underwriting in simple terms?
Underwriting is the process an insurance company uses to evaluate how risky it would be to insure a person, property, or business and decide whether to offer coverage.
Is an insurance underwriter the same as an insurance agent?
No. An insurance agent or producer generally works with customers to sell and explain insurance coverage. An underwriter evaluates applications and risk on behalf of the insurance company.
Do insurance underwriters sell insurance?
Underwriters generally evaluate insurance risks rather than sell policies directly to consumers. Insurance agents and brokers perform the sales function and are generally subject to state licensing requirements.
Do you need a degree to become an insurance underwriter?
A bachelor’s degree is the typical entry-level education for insurance underwriters, according to the BLS. However, some candidates with an associate degree or high school diploma and relevant insurance experience may qualify for positions.
Do insurance underwriters need an insurance license?
A producer license is not generally identified as a standard requirement for becoming an insurance underwriter. Individual employers and positions may have different requirements, so job candidates should confirm the qualifications for the particular role they’re pursuing.
Are insurance underwriters being replaced by AI?
Automation is reducing the amount of manual work required for routine underwriting decisions, and the BLS expects this technology to contribute to declining employment in the occupation. However, human underwriters continue to evaluate more complicated risks and situations that require additional analysis and judgment.
How much do insurance underwriters make?
The median annual wage for insurance underwriters was $81,370 as of May 2025, according to the U.S. Bureau of Labor Statistics. Actual earnings vary based on factors such as experience, location, specialty, and employer.